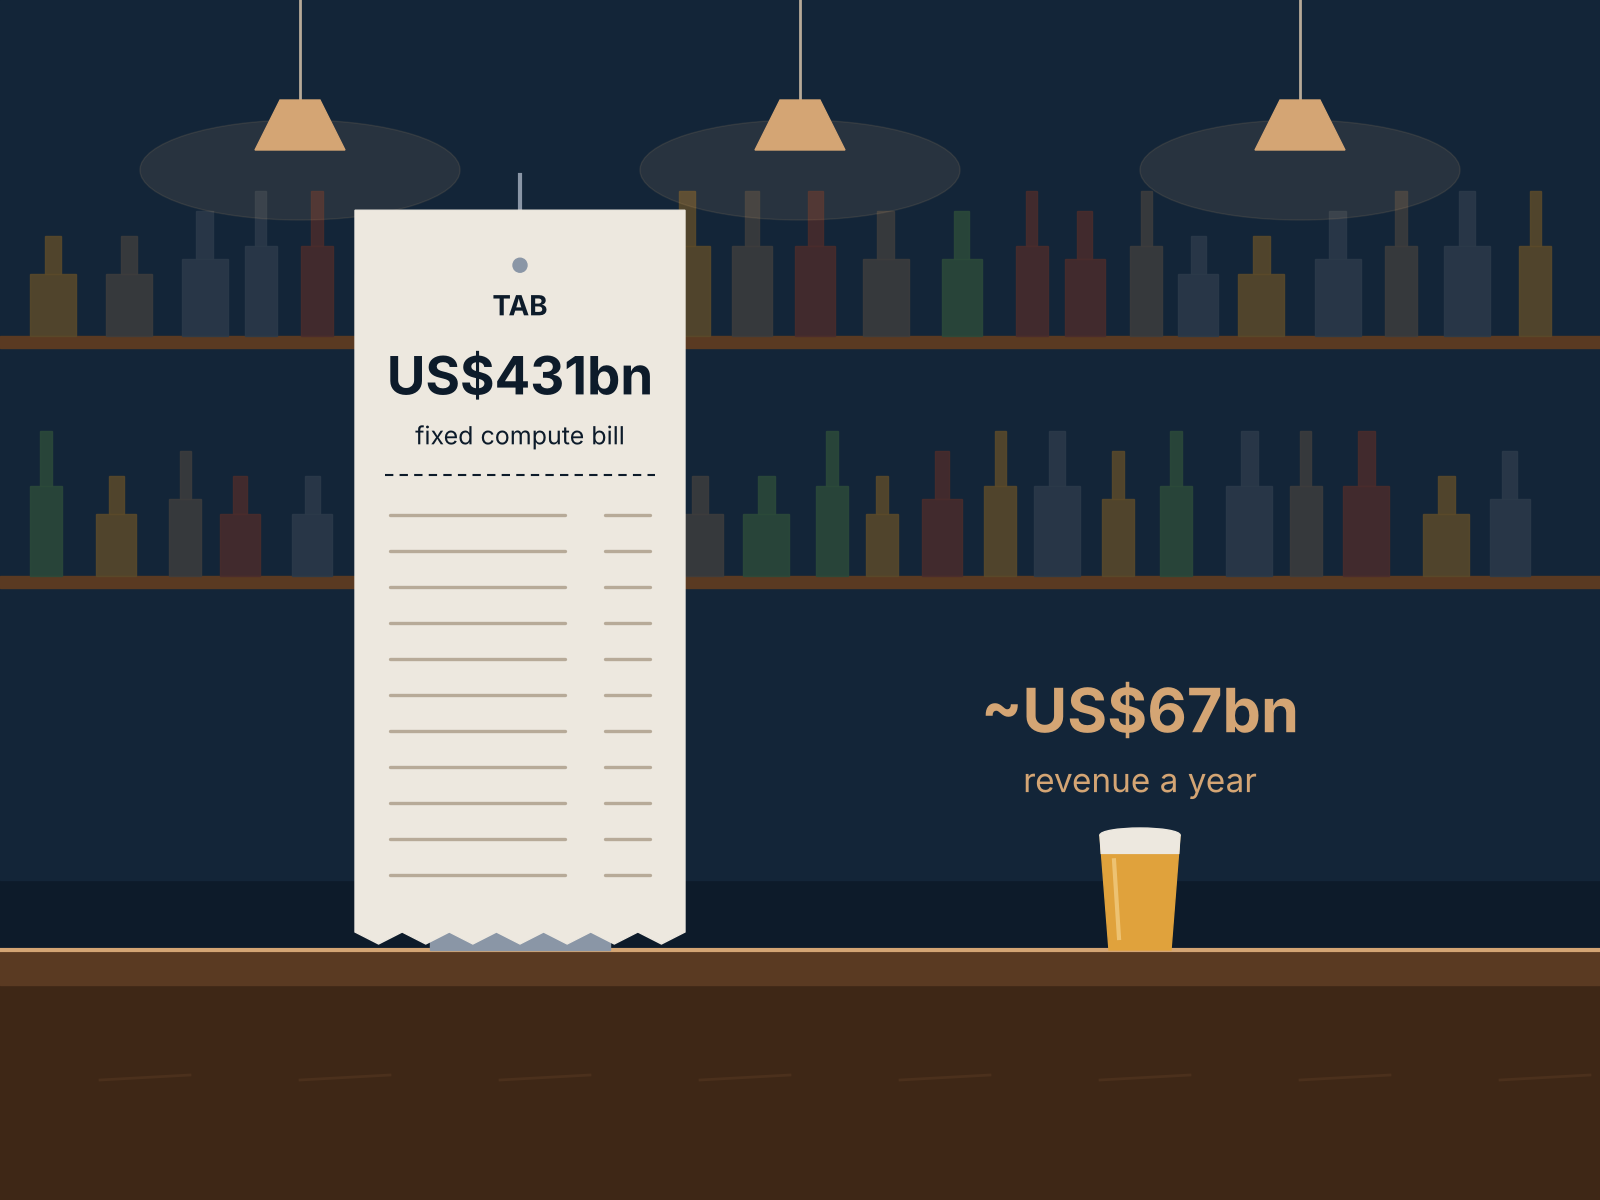
Anthropic's 26 October filing is the adrenaline shot this market has longed for: first-half revenue 14 times a year earlier, and a first operating profit. Nice shot. But a big tab is coming for the AI rockstar: the kind of bill that sank the telecom boom in 2000.
The 2000 story is AT&T Wireless: the right technology (3G mobile networks), a record IPO, sold weeks after the dot-com peak. Its IPO buyers still lost about half over four and a half years, by the time Cingular bought it out for cash in October 2004. So I put them side by side and had a proper think.
Anthropic's IPO valuation: bigger than May. So is the revenue.
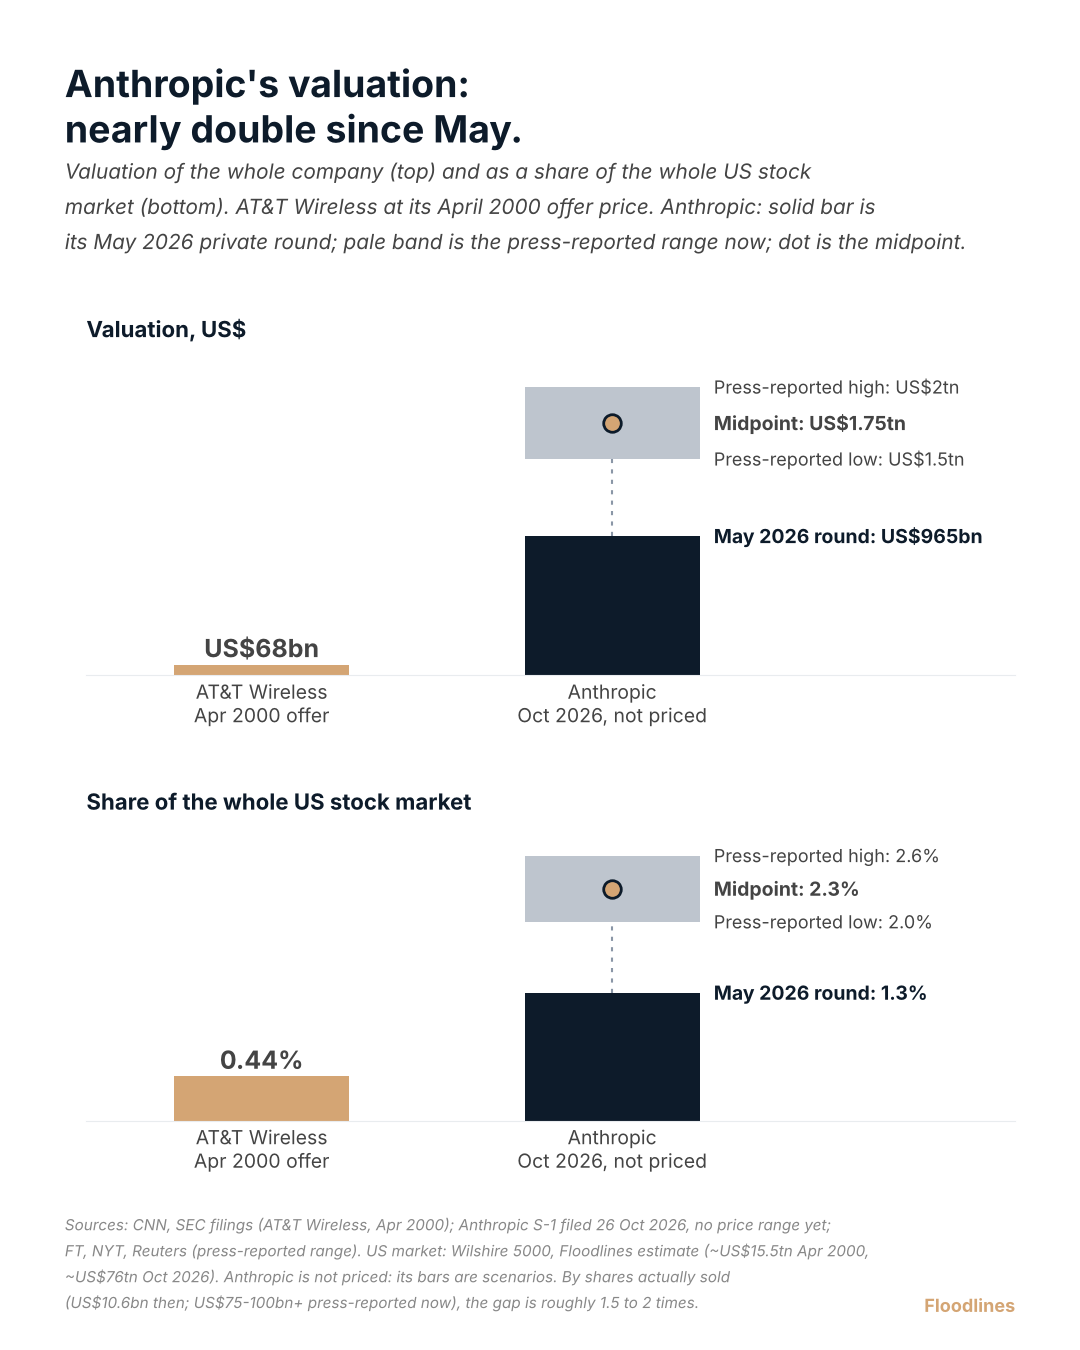
No formal price has been filed yet, but the press puts the IPO at US$1.5tn to US$2tn, well above May's US$965bn round. The reassurance is revenue, which has grown faster than the valuation: up about 260% in two quarters (management's figure) and first-half revenue is up 1,300% on a year earlier. AT&T Wireless grew 37% in its listing year.
At US$2tn, Anthropic would be about 2.6% of the US stock market, bigger than Meta or Tesla. AT&T Wireless was 0.44%. Four to six times the weight means far more influence on the market, and that could work both ways.
The adrenaline shot. Now the 2000s test.
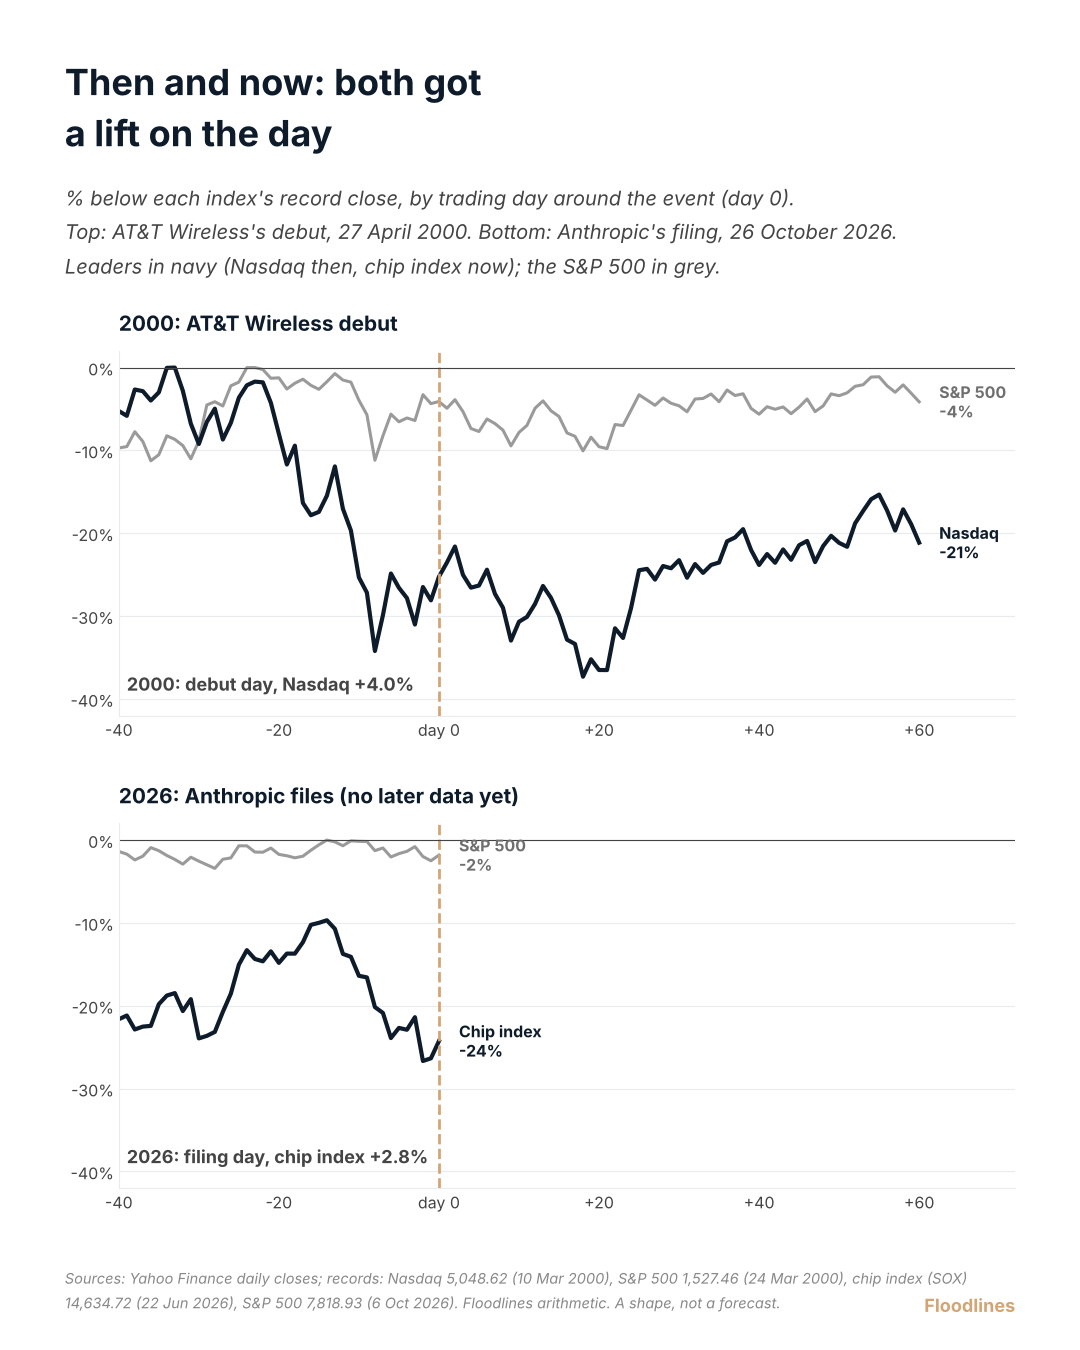
Anthropic's filing came with chips' best day in five weeks: the chip index (SOX) rose 2.8% on 26 October as the news landed. It's a boost to sentiment. But it's only one day. In 2000 the market got the same lift: the Nasdaq rose 4% on AT&T Wireless's debut day, 27 April, then sat 37% below its peak within a month. The Fed decision on 28 October and big tech earnings on 28 and 29 October are the real tests.
Déjà vu? Not quite. But we shouldn't take one day's performance as a firm guide.
Cash and revenue: what Anthropic brings to the test.
The 2000s story taught investors that the build-out and the technology can make sense while the market still won't back them, on sentiment or on cash. Today's investors could feel déjà vu and start to worry if they don't look closely at the differences.
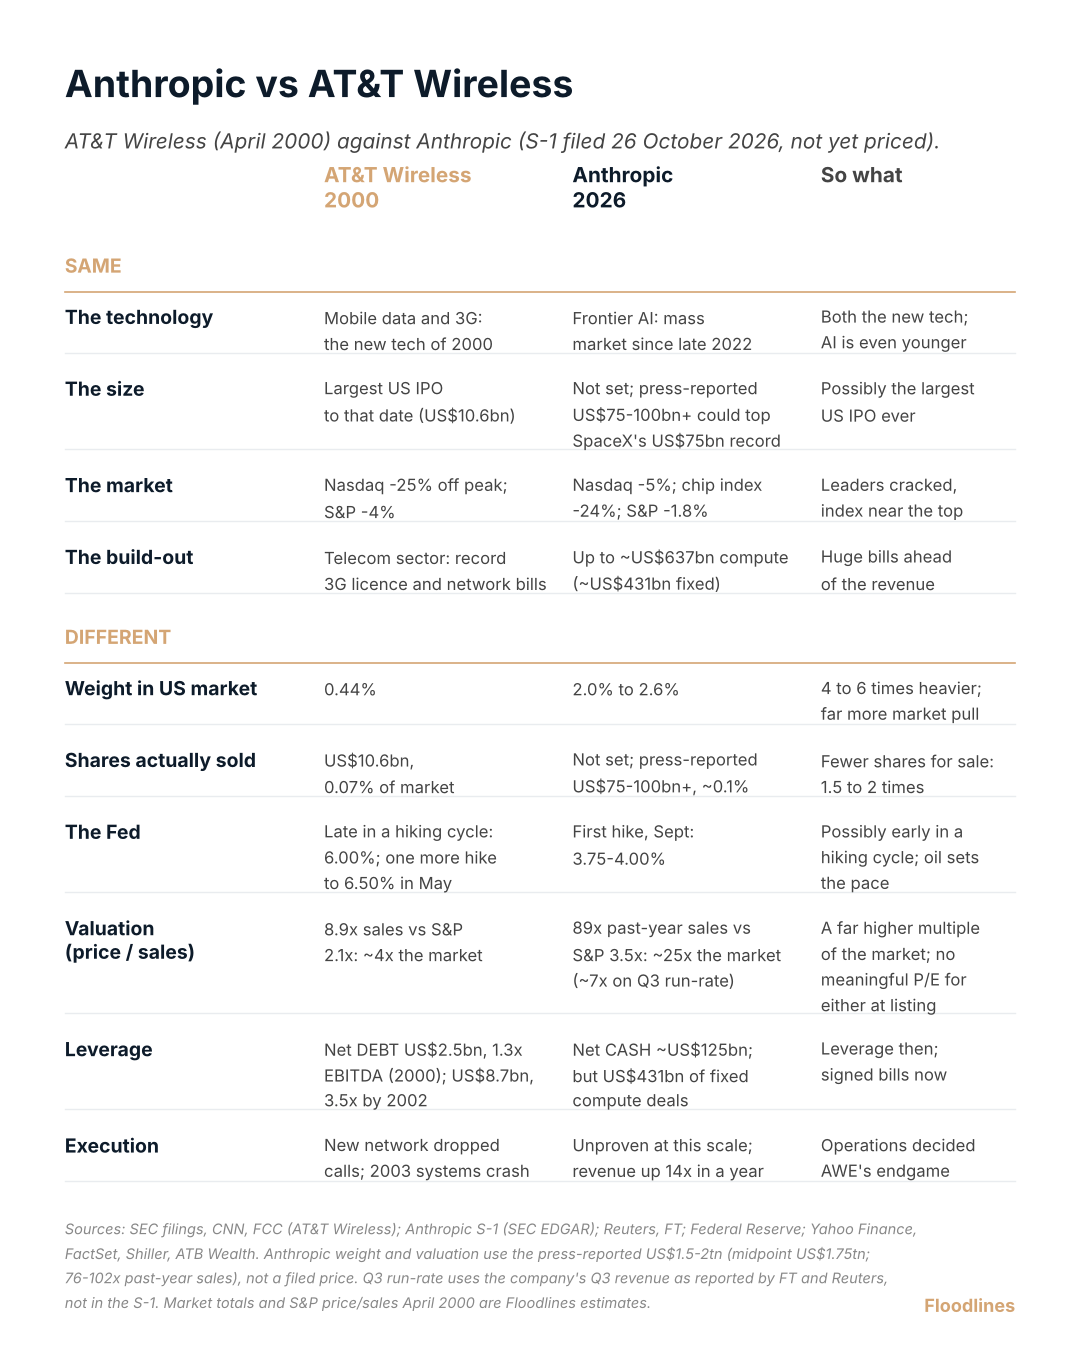
Anthropic stands out in two ways, and they answer the 2000 lesson directly:
- Cash. Net cash of about US$125bn, where AT&T Wireless carried net debt. In a higher-for-longer rate environment that counts for a lot, starting with less exposure to a credit shock through its own borrowing.
- Revenue. Up 1,300% in a year, with a first operating profit, against AT&T Wireless's 37% revenue growth in 2000. That growth starts to address investors' worry about profitability.
Pay the bill first. Then we can talk.
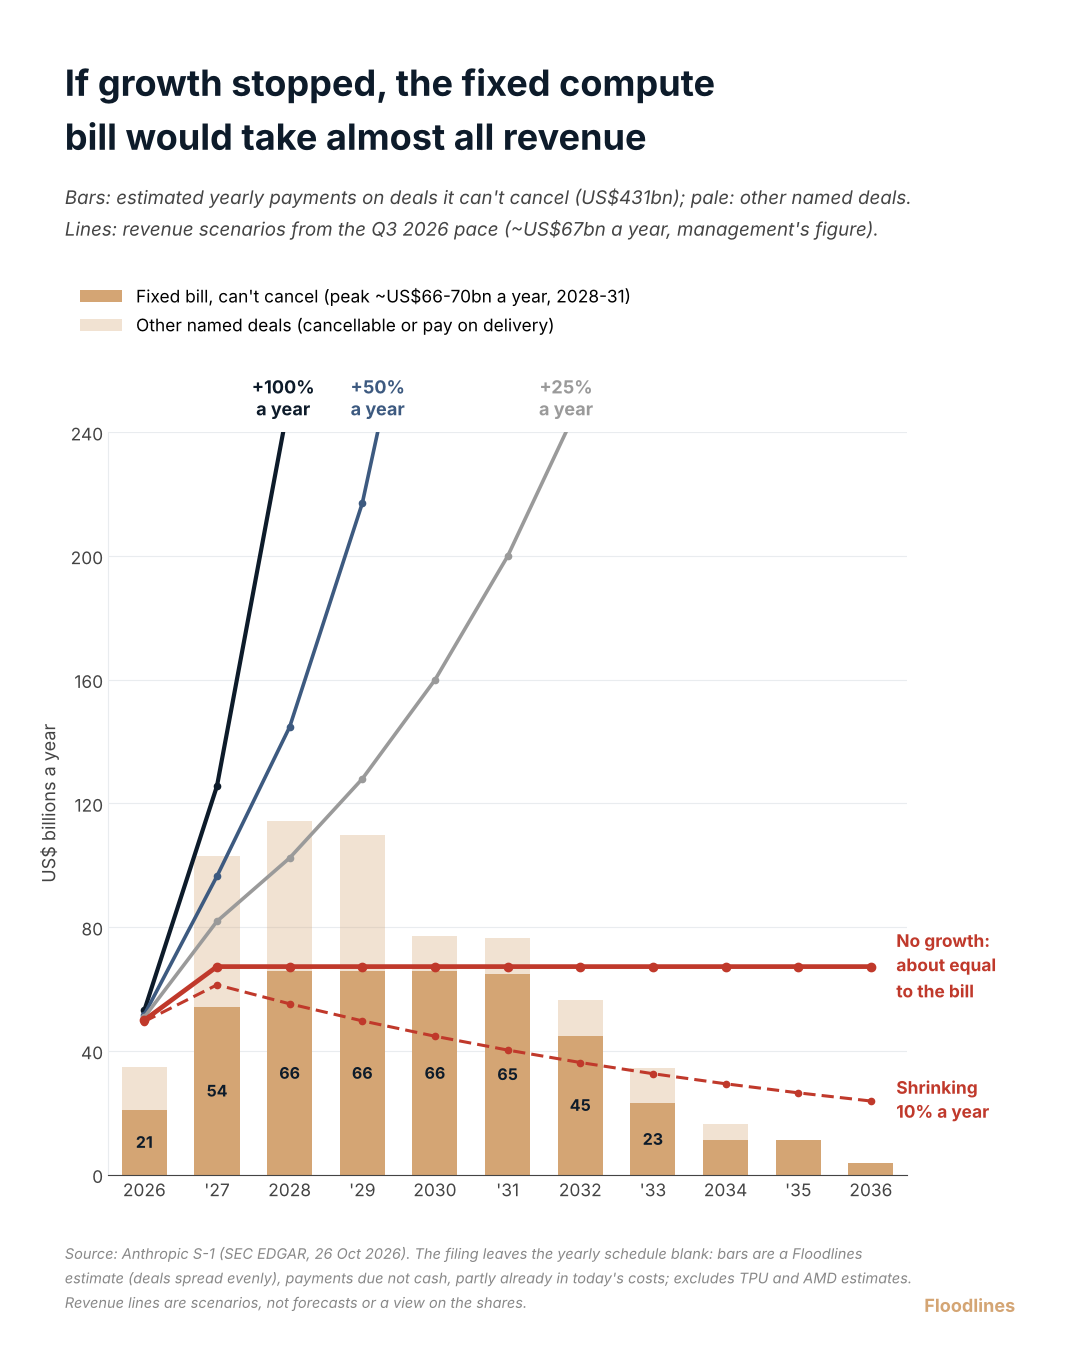
But we can't ignore the key challenge: its commitments. Anthropic is locked into about US$431bn of compute deals it can't cancel, with Broadcom, Google, Amazon and Microsoft (S-1). Counting chip leases, Fortune puts the total at up to US$750bn.
Our rough schedule (the filing leaves it blank) puts the fixed deals at about US$66bn to US$70bn a year from 2028: roughly what Anthropic earns now, about US$67bn a year. If growth stopped, they'd take almost all of it. To keep them under half of revenue, quarterly revenue needs to roughly double, to about US$32bn to US$33bn through 2028, which means growth of about 40% a year. That's the business test I'll watch. These are scenarios, not forecasts, and not a view on the shares.
History says year one after an IPO is tough.
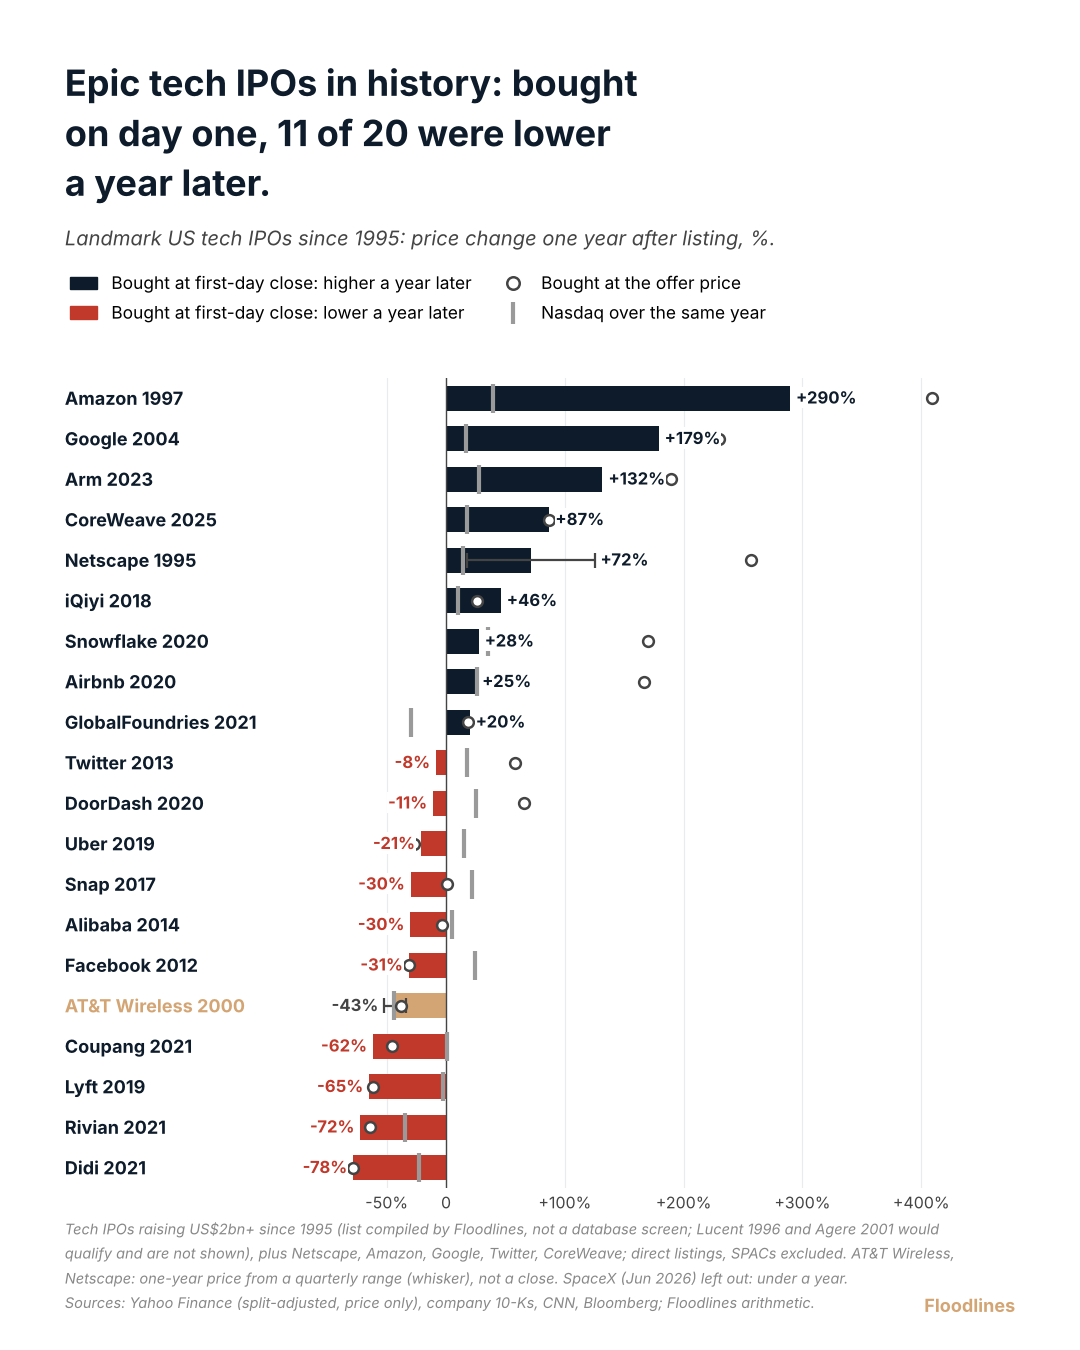
IPO allocations go mostly to institutions, so most investors buy once the shares trade. For those buyers, year one has historically been tough.
Take 20 landmark US tech IPOs since 1995. Bought at the first-day close, 11 were lower a year later and 12 trailed the Nasdaq; the median one fell about 10% while the Nasdaq's median gain was about 16%. Much of the gap is the first-day pop: 7 of the 8 that popped 38% or more trailed the Nasdaq. Over the first year, the record has favoured buyers at the offer price over those who bought once trading began. Past listings, not a forecast for any new one.
SourcesShow all 11Hide
- Anthropic, PBC, Form S-1, SEC EDGAR, filed 26 October 2026, accession 0001628280-26-067168, filing index: revenue (first half 2026 US$16,286m against US$1,163m; first quarter US$4,731m; second quarter US$11,555m); the second-quarter 2026 operating margin of 8%; cash and short-term investments of US$131,651m and operating cash flow of US$3,929m for the first half; total indebtedness of US$6.2bn (p.58); the Amazon notes (p.165); the rent note facility (p.167 to 168); the compute deals (p.171 to 173); the blank obligations schedule (p.170); commitments in Notes 7, 13 and 17. Net cash, the US$431bn non-cancellable sum, the US$637bn named-deal sum and the US$855bn all-in total are Floodlines arithmetic.
- Third-quarter revenue of about US$16.8bn: management's figure as reported by the FT and Reuters, via Khaleej Times; not in the filing.
- The May 2026 round of US$965bn: Euronews, 17 September 2026. The US$1.5tn to US$2tn range and the US$75bn to US$100bn-plus raise: press reports (FT, August 2026; New York Times; Reuters, 15 to 17 October 2026), never confirmed by the company. No offer price has been set.
- SpaceX's US$75bn IPO, 11 June 2026: Reuters via The Star, 12 June 2026.
- Size of the US stock market: about US$76tn in October 2026, a Floodlines estimate from Siblis Research (US$75.3tn, 1 July 2026) scaled by the Wilshire 5000; about US$15.5tn in April 2000, a Floodlines estimate from Wilshire 5000 data.
- AT&T Wireless: offer, size and first day, CNN Money, 26 April 2000 and 27 April 2000; quarterly price ranges, debt and network problems, 10-K405 for 2001 and 10-K for 2003; early 2004 prices, merger proxy, 22 March 2004; the US$15 cash buyout, Cingular 10-Q, 2004. The US$68bn value is Floodlines arithmetic (US$10.62bn raised for 15.6% of the group). OpenAI's confidential filing: OpenAI statement, 8 June 2026, as reported by Reuters and CBS News. Total compute commitments: Fortune, 26 October 2026. Magnificent Seven comparison: Yahoo Finance closing prices, 26 October 2026, times latest reported share counts, Floodlines estimate (Meta about US$1.6tn, Tesla about US$1.3tn). Revenue: US$10.4bn in 2000 (10-K405 for 2001); about US$7.6bn in 1999, Floodlines arithmetic from the IPO prospectus (US$68bn at 8.9 times 1999 sales).
- US wireless subscribers: FCC, Sixth CMRS Competition Report (109.5m at end-2000) and later reports (181.1m at end-2004).
- Rival wireless stocks to their 2002 lows: rival US wireless carriers' 10-K filings (Item 5), SEC EDGAR; Floodlines arithmetic.
- Market moves: Yahoo Finance daily closes for the Nasdaq Composite, S&P 500 and PHLX Semiconductor Index, read 26 October 2026; records: chip index 14,634.72 (22 June 2026), S&P 500 7,818.93 (6 October 2026), Nasdaq 5,048.62 (10 March 2000), S&P 500 1,527.46 (24 March 2000). Floodlines arithmetic. The press link between the chip move and the filing: CNBC, 26 October 2026.
- Tech IPOs, year one: Yahoo Finance (split-adjusted, price only), company 10-K filings, CNN, Bloomberg and Renaissance Capital. The list is compiled by Floodlines, not a database screen: US tech IPOs raising US$2bn or more since 1995, plus Netscape, Amazon, Google, Twitter and CoreWeave; direct listings and SPACs excluded.
- The Fed: Federal Reserve, 16 May 2000; the 16 September 2026 decision, Federal Reserve release. This week's dates: Federal Reserve calendar, BEA release schedule and each company's investor relations page.
Currency: US dollars. Quarters are calendar quarters. Anthropic has filed to list but has set no offer price; every Anthropic valuation here is press-reported, not filed.
Company, index and benchmark names are trade marks of their owners and are used only to identify the companies, indices and benchmarks concerned. No company, index owner, benchmark administrator or data publisher named here sponsors or endorses Floodlines.
Important information
General information only. Floodlines is not licensed to provide financial product advice, and nothing here is a recommendation to buy, hold or sell. The author holds no position in any company named and has not applied for Anthropic shares in the IPO. Floodlines is not a registered investment adviser.
Show full termsHide full terms
Important. Floodlines publishes independent research and commentary on the economy, markets, industries and supply chains. It is general information only. Floodlines is not licensed to provide financial product advice and does not provide it. Nothing here is a recommendation to buy, hold or sell any financial product. Nothing here has been prepared by reference to any reader’s objectives, financial situation or needs, and Floodlines does not respond to individual questions about personal circumstances, holdings or portfolios. Views are the author’s own as at the date of publication, may change without notice, and may be wrong. Where a piece says how sure the author is of a view, or what would change her mind, that describes her confidence in her own reading of events. It is not an instruction to any reader. Before making any financial decision, obtain advice from a licensed financial adviser and consider the relevant product disclosure statement or offer document. Where a piece reports the author’s past calls, it is a record of her own process, wrong calls included. Past calls are not an indicator of future performance.
Interests. Companies appear in this piece as businesses, never as investments. Floodlines pays to use Anthropic's Claude in its research and has no other relationship with Anthropic or its underwriters. The author holds no shares, bonds, options or other securities in any company named in this piece or its charts, directly or through an account she directs, and has not applied for Anthropic shares in the IPO. Floodlines receives no payment from any issuer, underwriter or dealer in connection with any security discussed.
United States readers. Floodlines is a publication of general and regular circulation. It provides impersonal commentary only, does not provide personalised investment advice, does not hold itself out as an investment adviser, and is not registered as an investment adviser with the SEC or any state. Floodlines will not answer questions about your portfolio or circumstances. Floodlines receives no compensation from any issuer, underwriter or dealer in respect of any security discussed.